





Аналитика и комментарии
Bank’s Profitability
The profits generation is the main objective of any commercial bank, which plays an important role, at the same time, for several participants of legal relationships: shareholders, borrowers, depositors. Meanwhile, the bank’s profitability, calculated as a difference between aggregate yields and incurred expenses shows how effective the bank’s operations are.
Form 101 may be used to calculate the profitability rates as per the Russian Accounting Standards. In addition, the banks have to fill quarterly Form 102 "Profit and Loss Account", which contains an itemized list of the bank’s incomes and expenses YTD. Net operating income and net interest income are the main indicators, used to evaluate financial performance of a financial institution.
Net operating income shall be calculated as a difference between operating income and operating expenses of the bank. The operating income includes, in particular, proceeds from securities operations, bank’s interests in third-party companies and fees. Operating expenses include, among others, expenses for securities-related transactions, negative revaluation results for precious metals, foreign currency, generation of possible losses reserves, personnel payroll, property purchases for the bank.
Net interest income is a difference between all interest income items, derived from deposited loans, and all interest expenses, arising, among others, out of issues of bonds and promissory notes, customers’ deposits and loans attraction
As a rule, a portion of the bank’s profits is furnished to the Charter capital and other accumulation funds, special-purpose fund and reserve fund. In addition, the bank’s profits are used to pay the dividends to its shareholders. The profits, furnished to accumulation funds and special purpose funds, are expended to purchase PPE, delivery of consumer and charity projects, bank’s personnel training.
A distribution of profits to financial institutions, having interests in the bank, is regulated by the Federal Law "On Joint Stock Companies", setting forth the methods for the general shareholders meeting to distribute funds based on the annual performance results. The exemption covers any profits that were distributed in the form of dividends based on the results for Q1, H1 and Q1+Q2 of the financial year.
It should be noted that a distribution of dividends is a right and not an obligation of a joint stock company. The shareholders meeting may resolve not to pay any dividends to common stock holders (while dividends have to be paid to preferred stock holders in any event) and instead use the funds to achieve other objectives.
Taking into account a highly competitive environment, the banks need to develop a well-thought product line, seek to focus the target audiences, clearly identify a rationale for opening new SBUs, look for promising banking business lines and ensure effective advertising support.
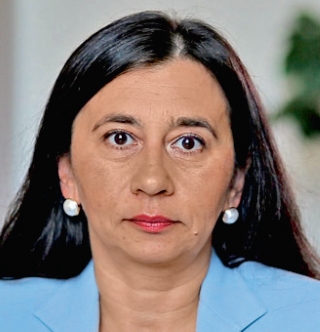
Svetlana Khokhlova,
Сhairman of the Board
of SOCIUM-BANK LLC
NBJ: Your bank managed to attain high KPIs for growth rates in profit, assets volumes and credit portfolio. What were the methods that enabled you to reach such results?
S. Khokhlova: We have actively worked to draw new customers, managing to grow our passive customers base even in the turbulent times, when many banks go bankrupt. The bank has always striven to act a reliable and stable partner with a focus on the B2B segment.
NBJ: In addition, the bank managed to grow profits by 135%, which is extremely surprising in the current difficult conditions. How did the bank’s team manage to attain such results?
S. Khokhlova: In addition to the activities by the bank’s cost optimization team, our clients and partners also made a great contribution, as they, despite the unfavorable financial environment, did not fall for panic and retained funds on their accounts and deposits. They understood the necessity to change the rates for both raised and invested assets and displayed a financial discipline and a resistance to crisis developments.
NBJ: What plans does the bank have for 2015?
S. Khokhlova: In spite of high results for H1, the bank has a cautious outlook for future economic development in the country, and the main objective will be to help customers resolve any issues, arising in their businesses.
NBJ: Does the bank have any plans for 2016?
S. Khokhlova: We have always worked in line with the developed strategy, seeking to ensure sustainable performance, while we will identify operational performance objectives closer to the beginning


